AI Communications

Learn how voice-first AI, unified communications, and intelligent automation help you deliver seamless, secure customer experiences across every channel.
Your customers hold accounts they barely think about until something goes wrong. Then a card gets declined at the worst moment, a transfer stalls, or a fraud alert lands at midnight, and suddenly the entire relationship rides on one interaction.
Many banks pour budget into mobile apps and digital channels, but customer satisfaction keeps plateauing. The reason is rarely the banking app itself. It’s the seams between channels. A customer starts in chat, gets pushed to the phone, then repeats their account number to an agent who can’t see what just happened. Every handoff chips away at trust.
The pressure runs in two directions at once. Customers expect fast, personal service on every channel. Boards expect lower cost-to-serve and a return on the technology already bought. Closing that gap means fixing the connective tissue between branches, contact centers, and apps, not adding another point tool.
This guide breaks down what customer experience in banking actually covers, the trends reshaping it, the metrics that prove progress, and a practical path to improve it with AI. You’ll get the levers that move satisfaction and the obstacles that stall most programs, so you can build a case your team can act on.
Key takeaways
- Voice-first AI can reduce channel silos
- Voice remains critical for urgent financial issues
- Automation frees specialists for high-value interactions
- Conversation intelligence turns interaction data into action
What is customer experience in banking?
Customer experience in banking is the sum of every interaction a customer has with a financial institution, across branches, mobile apps, call centers, websites, and ATMs. It covers how easily people can open accounts, resolve problems, and get advice, and how consistent, secure, and personal those moments feel from start to finish.
In practice, customer experience in banking plays out across the whole journey: onboarding an account, servicing a loan, disputing a charge, or getting help after a fraud alert.
What defines exceptional customer experience in banking today, and what trends are reshaping it?
Exceptional customer experience in the banking industry means customers get what they need quickly, safely, and consistently—regardless of channel. While friendly branch service and functional mobile apps remain important, the new standard is a single, coherent experience across every touchpoint.
It matters because banking is often a daily digital habit, and the institutions that connect their channels keep customers who would otherwise drift to a competitor with a smoother app. Customers expect fast, personalized, consistent service, and they expect it on whatever channel they happen to be using.
That expectation grew as banking went mobile. Between 2020 and 2023, consumer use of cell phones for banking rose to 57%, up 18 points from 39%, according to McKinsey.
To keep pace, banks need to provide:
- Quick recognition and authentication without making customers repeat themselves across channels.
- Fast, accurate answers for routine requests and immediate routing to experts for complex needs.
- Round-the-clock self-service and live help by phone, chat, or messaging.
- Proactive personalization that remembers preferences and anticipates needs.
- Security and transparency that prove you protect customer data and act in customers’ best interests.
Behind the scenes, contact centers, branches, and back-office teams need to work from shared information. That internal alignment is what makes external trust possible. On top of that, transparent fee communication and clear next steps matter as much as fast response times. The most effective experiences balance efficient AI-assisted service for routine needs with human advisors ready for the high-value conversations that call for judgment and empathy.
The three trends below are reshaping what “good” looks like, and each one raises the operational bar for CX and contact center teams.
Voice-first AI reimagines your most critical channel
Phone calls remain the channel customers choose for urgent or complex issues that require an emotional connection. AI-enhanced communications now understand intent and verify identity to either resolve issues or route calls to the right specialist, making your most high-stakes channel more efficient without sacrificing service quality.
This same technology is also a defense mechanism. According to Deloitte’s 2026 Banking and Capital Markets Outlook, banks face a growing number of malicious AI agents designed to mimic human behavior and evade detection. In modern banking, secure, intelligent AI infrastructure is a strategic necessity.
RingCentral’s voice-first AI is built to address both sides of this challenge, automating and personalizing customer interactions while enforcing consistent security policies, authentication, and compliance controls across every channel.
Unified communications break down operational silos
Banks are replacing separate tools for internal collaboration and customer engagement with integrated platforms that combine calling, messaging, video, and contact center capabilities.
RingCentral brings RingEX (employee communications) together with RingCX (customer engagement) so your teams coordinate around customer needs in real time, regardless of location.
Real-time analytics turn conversations into action
Every call, chat, or video interaction signals customer sentiment, product issues, and process friction. Modern, unified platforms transcribe, summarize, and analyze these conversations at scale, showing what truly drives satisfaction.
Moving away from point solutions provides immediate value: consistent authentication and security policies across channels, shared context across teams, standardized reporting to compare performance across branches and queues, and reduced vendor sprawl.
When you treat every experience as an end-to-end conversation, you can adapt quickly as expectations evolve. Institutions that execute this consistently see higher loyalty, lower churn, and greater share of wallet.
Why customer experience in banking matters
Better customer experience in banking pays off in retention, share of wallet, and lower switching risk, and the gap between leaders and laggards is widest among the customers most likely to leave. In a market where switching a bank account takes minutes on a phone, customer experience can become a meaningful source of retention.
Digital-native banks have made that case most vividly. Bain & Company found that three popular digital-native banks kept account opening failure rates below 2% while also ranking at the top of nationwide Net Promoter Scores (NPS) for overall relationships. Low-friction onboarding and high loyalty scores tend to travel together.
Personalization compounds the effect. In the past, companies that employed advanced personalization models generated 5% to 15% higher revenues from their enhanced campaigns and halved or quartered their time to market, according to McKinsey. For a bank, that translates into relevant offers at the right moment instead of generic cross-sell.
US neobanks show the same pattern. Chime reported strong relative performance in a 2025 Qualtrics NPS study, and its customer loyalty consistently ranks among the highest in US banking. Signals like these explain why legacy providers keep investing to close the experience gap. A strong CX score is one of the clearest early signals of a customer who stays and buys more.
How can banks improve customer experience in banking?
Banks can improve customer experience by pulling three levers in order:
- Unify channels so customers stop repeating themselves
- Automate routine journeys so agents focus on complex needs
- Coach agents with real-time data so quality holds at scale
Start with the friction customers feel most—usually the handoffs between channels—and work backward to the systems causing it.
Use AI and automation to connect banking journeys
Fewer repeat contacts and faster resolution start with automating the journeys that clog your queues, such as balance checks, card activation, password resets, and routine disputes. Route those to AI, and your agents get room for the conversations that actually need a person.
The problem most service teams hit is visibility. When routing, quality management, and analytics live in separate tools, agents work blind and supervisors can only review a tiny sample of calls. Solutions like RingCX unify voice, chat, text messaging, email, and social in one agent workspace and run AI quality management across 100% of interactions, so bank service teams act on every conversation instead of a sampled few.
That coverage turns quality assurance from a spot check into a continuous feedback loop, and it shortens the path from a customer complaint to a fixed process. Pair automation for routine tasks with real-time agent guidance, and resolution times can drop without adding headcount.
Integrate omnichannel strategies across physical and digital touchpoints
Treat your bank as a single entity—your customers expect you to recognize them and pick up where the last interaction left off, regardless of channel. Delivering this customer experience best practice requires a deliberate omnichannel strategy and the right platform.
Use a unified communications platform like RingCentral to:
- Deliver consistent experiences whether customers call, chat from your app, or visit a branch
- Enable branch staff to reach contact center experts or back-office teams instantly via voice, messaging, or video
- Share context across channels so agents and bankers see recent interactions, notes, and open cases
- Standardize recording, retention, and security policies across all customer-facing channels
Because RingEX and RingCX share the same platform, your employees move seamlessly between serving customers and coordinating with colleagues without switching tools or losing context. This convergence simplifies operations: your employees work within a single interface that follows them across devices and locations, accelerating adoption, shortening training time, and reducing errors that impact customer experience.
Orchestrate your customer journeys intentionally with unified touchpoints that start with mobile self-service, escalate to voice support when needed, and transition to a scheduled video meeting with a specialist for complex advice. This continuity acts as a critical differentiator for leading institutions looking to create customer-centric experiences.
How do banks measure and optimize customer experience in banking?
Improving customer experience in banking starts with meaningful, manageable measurement. Visibility across channels, products, and segments connects frontline customer support activity to business outcomes, including retention, growth, and cost-to-serve.
Traditional metrics like call volumes and average handle time matter, but they don’t tell the whole story. Combine operational metrics, customer sentiment indicators, and outcome-based measures—all fed by consistent, high-quality data—to understand how your bank truly performs.
Cloud communications platforms with embedded analytics and conversation intelligence capture and analyze interactions across voice and digital channels. You see exactly where customers get stuck, which processes cause repeat contacts, and where specific teams excel—without building everything from scratch.
Essential metrics and KPIs for banking CX success
Track metrics that connect directly to action and business outcomes. Focus on:
- Customer satisfaction (CSAT): Captures how customers feel about specific touchpoints right after an interaction. Small changes here often flag process friction before it shows up in churn, so it pays to deliberately track CSAT across your contact center.
- Net promoter score (NPS): Measures loyalty and advocacy, showing whether satisfied customers become advocates over time. Build NPS into your customer care strategy rather than treating it as a standalone survey.
- Customer effort score (CES): Reveals how easily customers complete goals like disputing a transaction or opening an account.
- First-contact resolution (FCR): Tracks issues resolved in one interaction, a key driver of both satisfaction and cost efficiency.
- Average handle time (AHT): Measures efficiency; read it alongside quality and FCR so you never reward rushing complex conversations.
- Self-service success and containment: Shows how often customers finish tasks through automated channels without live help.
- Complaint volume and resolution time: Signals process friction and flags areas that draw regulatory scrutiny.
- Employee experience metrics: Agent satisfaction, attrition, and schedule adherence all feed directly into customer outcomes.
Connecting these metrics to business results provides the context needed for improvement. Analyze call transcripts, sentiment, and topics at scale to identify pain points, training gaps, and process issues that customer feedback surveys miss. Then, pair the numbers with conversation-level customer experience analytics for the full picture. Use those insights to refine interactive voice response (IVR) flows, update knowledge bases, and staff for peak periods.
A successful strategy relies on a CX governance rhythm where operations, IT, risk, and business leaders review shared dashboards, set priorities, and track progress. Embed measurement into your operating model to make optimization continuous, not episodic.
Common challenges to improving customer experience in banking
The biggest blocker to better customer experience in banking isn’t strategy. It’s data that teams can’t reach. In Grant Thornton’s 2026 AI Impact Survey, close to a third of banks pointed to poor data quality and integration as the thing stalling their AI efforts, with siloed systems that were never built to talk to each other sitting at the root of the problem. When an agent can’t see a customer’s history in the moment, no amount of CX vision fixes the interaction.
A few obstacles show up in almost every program:
- Data silos: Customer information sits in separate systems that don’t talk to each other, so agents piece together context by hand.
- Legacy core systems: Decades-old cores make it slow and risky to change customer-facing journeys.
- AI that stalls at pilot: Promising proofs of concept never reach production, so the value never lands.
- Compliance constraints: Recording, retention, and data-residency rules shape what you can automate and where.
None of these are permanent. Each maps back to the levers above. Unify the channels and data first, then automate on top of a clean foundation, and bring risk and compliance in early so governance enables change instead of blocking it.
How can banking leaders future-proof customer experience strategies?
Future-proofing customer experience means building an architecture that absorbs change, whether that is new regulations, emerging channels, evolving threats, or shifting expectations, without constant reinvention. In concrete terms, it requires a platform that unifies channels, keeps voice at the center, covers 100% of interactions, and treats security as part of the design rather than a later add-on.
Most AI programs aren’t there yet. Deloitte’s 2026 Outlook found that only 4 out of 50 banks analyzed in 2025 reported AI-driven ROI. The banks that pull ahead are the ones moving AI from pilot to production on a foundation that scales.
Voice remains the anchor of this strategy. Even as digital adoption grows, customers choose phone conversations for high-value moments: major purchases, financial distress, fraud, or complex advice. Effective strategies prioritize voice as the foundation, augmented by AI and integrated tightly with digital channels and core systems.
Security and compliance must be integral, not bolted on. Cloud communications providers like RingCentral build in encryption, granular access controls, robust audit logging, and configurable policies for recording, retention, and data residency—supporting your obligations across regions and regulatory frameworks.
Prioritize platforms that deliver:
- Cloud-native scalability that lets you adapt capacity, support hybrid work, and roll out changes across branches and contact centers
- API-first integration to connect communications with core banking systems, CRMs, fraud tools, and compliance platforms without creating new silos
- AI-ready architecture to deploy tools like RingCentral AI Receptionist, AI Virtual Assistant, and AI Conversation Expert where they deliver value
- Enterprise-grade reliability from partners that meet your expectations for uptime and long-term roadmap alignment
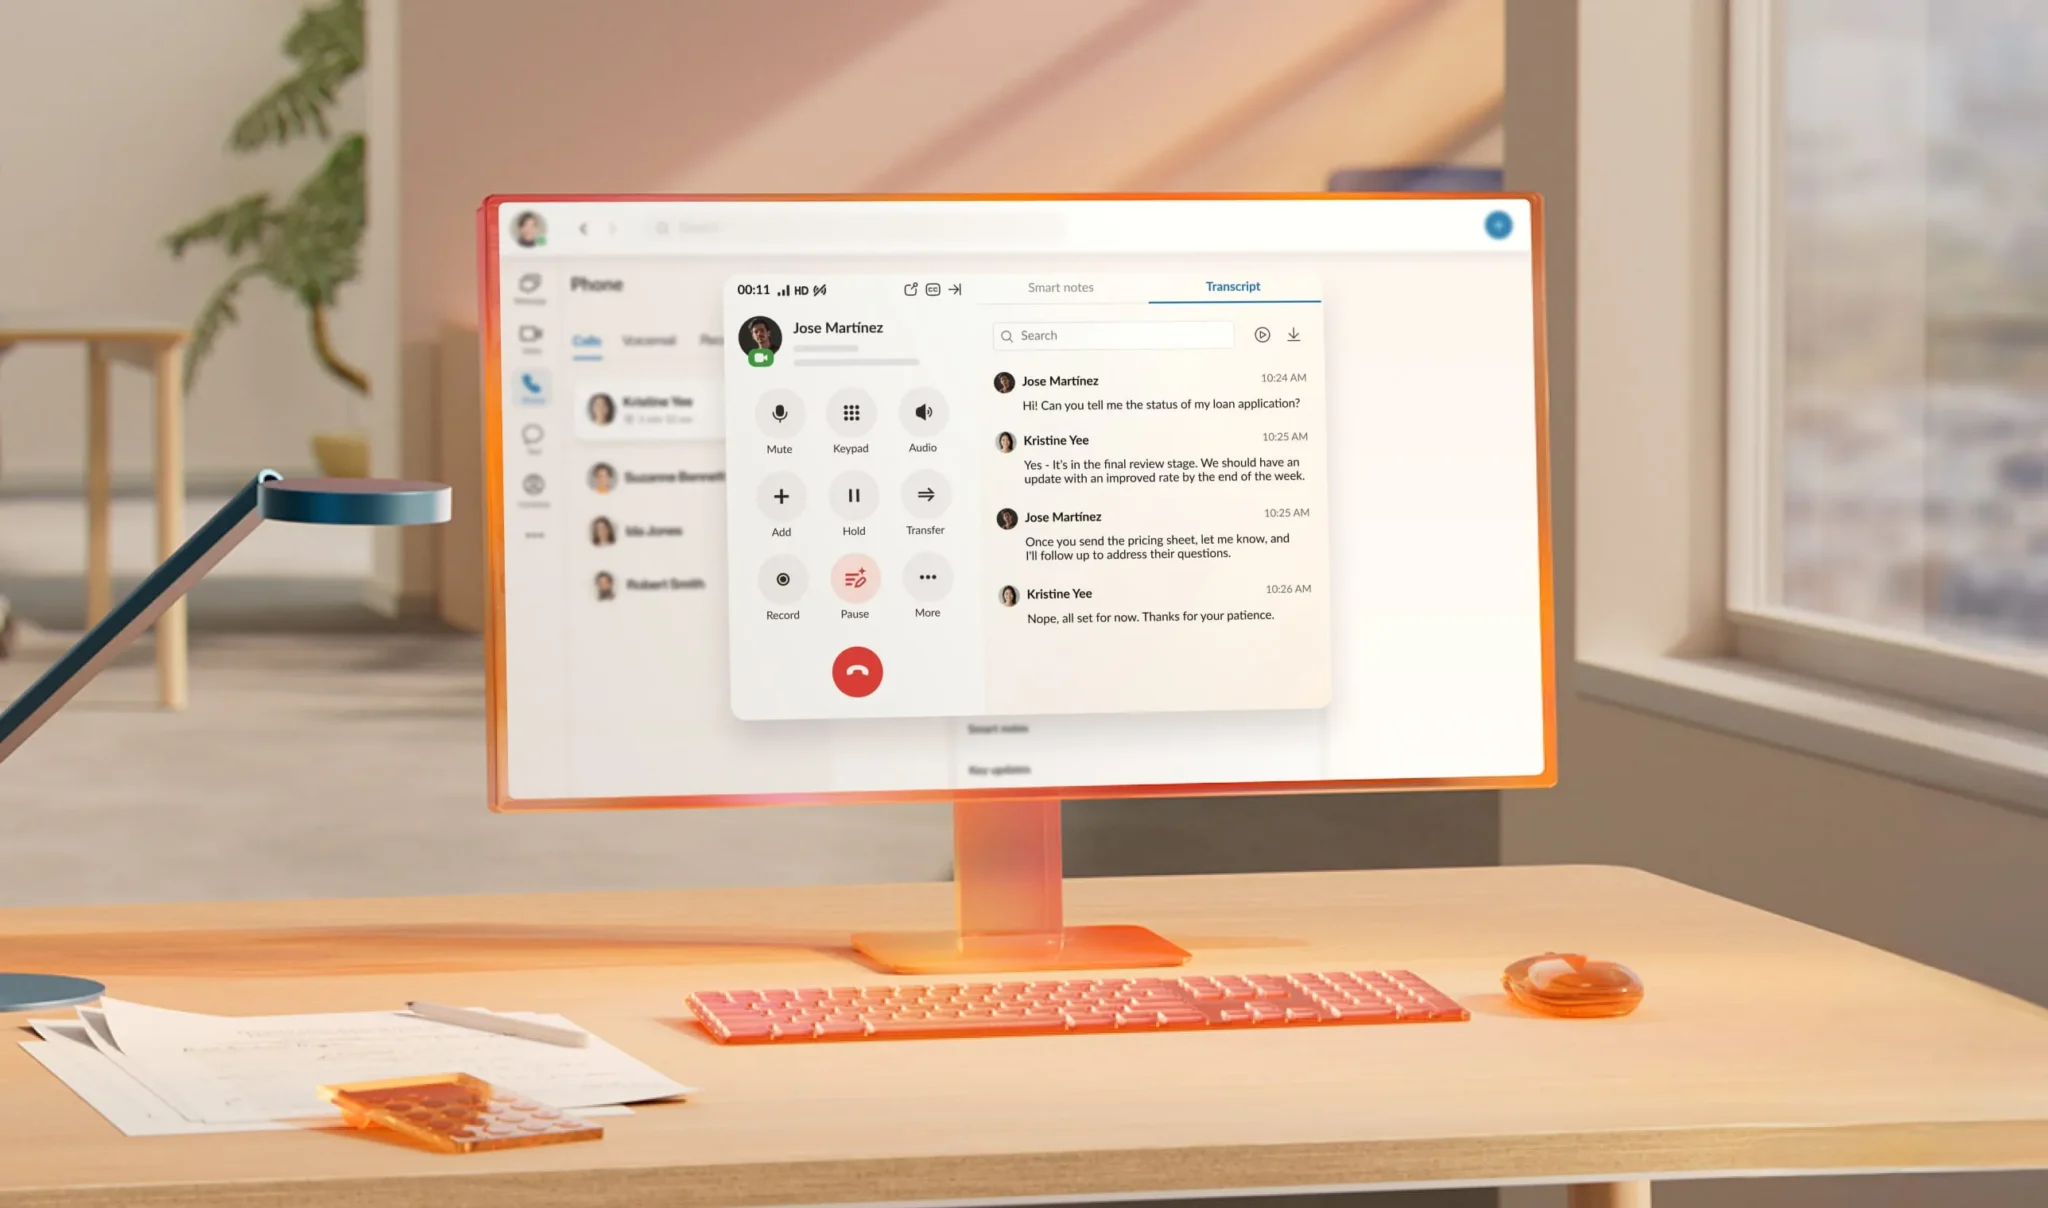
To put this into practice, execute a phased, outcome-driven approach:
- Link your CX vision to business initiatives like reducing time-to-resolution, improving digital UX, or strengthening retention in key segments
- Consolidate fragmented communication tools to simplify your environment and enable consistent AI and automation
- Pilot voice-first AI in defined use cases (authentication, card support, appointment scheduling), then measure impact and iterate
- Scale successful patterns across channels and regions while embedding governance with risk, legal, and compliance teams
- Refine journeys continuously using data analytics and conversation intelligence to stay aligned with customer needs and regulatory expectations
A phased customer experience plan keeps a contact center improving as customer needs and rules keep changing.
Ready to transform customer experience in banking?
Customer experience in banking comes down to continuity, evidence, and follow-through. Connect every channel, put voice-first AI to work, and measure the outcomes that matter, and CX stops being a vague aspiration and becomes a number you can move. The gains are real, and they show up in CSAT, NPS, FCR, and retention.
A few next steps for your institution: audit your communications stack for silos and gaps, define the CX outcomes you want to move, pilot voice-first AI in a high-volume use case, and build cross-functional governance with operations, IT, risk, and compliance.
See how RingCentral helps banks unify customer conversations and connect CX gains to the metrics that matter. Explore RingCX for your contact center.
FAQs about customer experience in banking
What are the 5 C’s of customer experience in banking?
The 5 C’s are commonly described as customer, cost, convenience, communication, and consistency. In banking, they translate to knowing the customer, keeping service affordable and efficient, making access easy across channels, communicating clearly about fees and next steps, and delivering the same quality everywhere.
What are examples of good customer experience in banking?
Good examples include opening an account from a phone in minutes, disputing a transaction in chat and resolving it in the same session, and calling about a loan to reach a specialist who already sees your history. Each one removes friction and spares the customer from repeating themselves.
How do banks measure customer experience?
Banks measure it with a mix of CSAT, NPS, customer effort score, first-contact resolution, and average handle time, backed by self-service containment and complaint resolution times. Read together rather than in isolation, these metrics show both how customers feel and how efficiently the bank serves them.
Why is customer experience important in banking?
Customer experience is important in banking because it affects trust, loyalty, retention, and how likely customers are to use more services over time. When customers can get help quickly, move across channels without repeating themselves, and resolve issues securely, they are more likely to stay with the institution.
Updated Sep 02, 2026